Should You Buy Hewlett Packard Enterprise (HPE) Right Now?
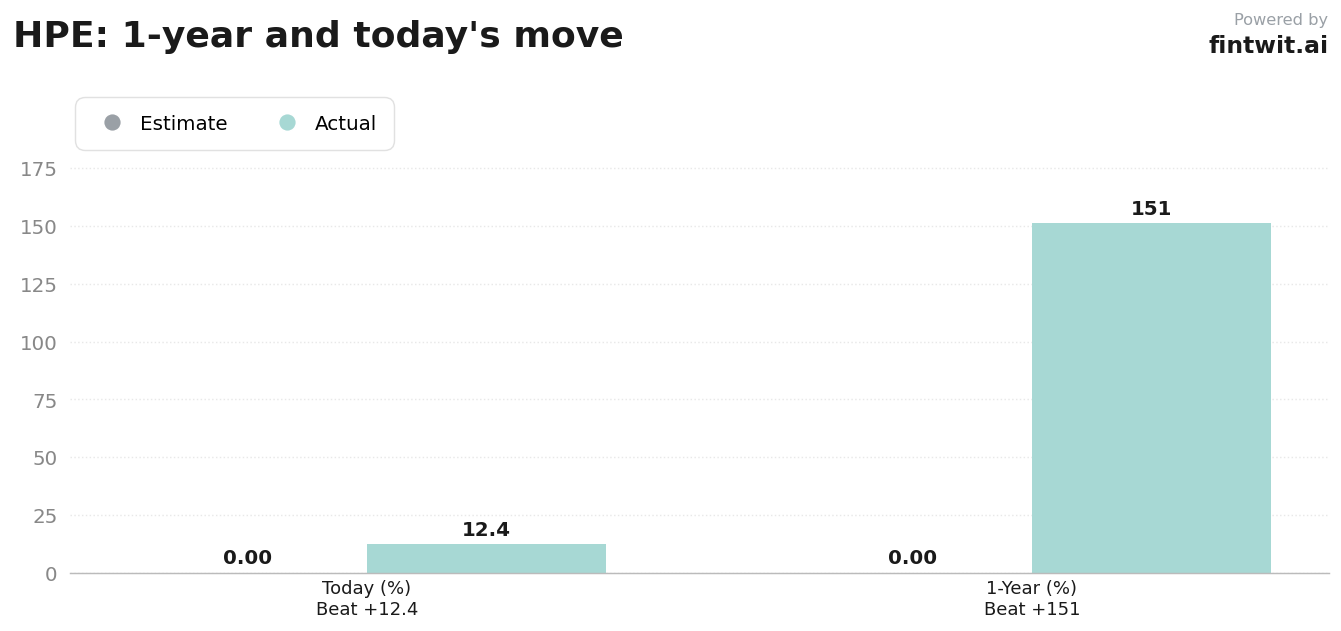
Hewlett Packard Enterprise (HPE) stock jumped 12.44% today, September 14, 2026, driven by Oracle's reiterated capital spending guidance.
What just happened
Hewlett Packard Enterprise (HPE) shares rose 12.44% today, September 14, 2026. This surge followed Oracle's reiterated fiscal 2027 capital spending guidance, which projected $90 billion to $95 billion for the year. Investors viewed this as a strong signal for increased demand in AI racks, networking gear, and data center hardware, all key offerings from HPE.
The company also recently reported record quarterly results for fiscal Q3 2026, with revenue up 34% year-over-year to $12.2 billion. AI server purchase commitments saw a fivefold increase in a single quarter, rising from $6 billion to $30 billion. This performance underscores HPE's growing position in the AI infrastructure market.
Bull case
HPE's strong performance and outlook are largely tied to the accelerating demand for AI infrastructure. The company has demonstrated significant momentum in securing large AI server commitments and delivering robust financial results. Its strategic positioning in the hardware supply chain for cloud and AI initiatives provides a substantial tailwind.
- HPE reported record fiscal Q3 2026 revenue of $12.2 billion, a 34% year-over-year increase.
- AI server purchase commitments surged fivefold in one quarter, from $6 billion to $30 billion.
- The company raised its fiscal 2026 and 2027 outlooks, forecasting fiscal 2027 revenue growth of 13% to 17% and EPS growth of 16% to 20%.
- Networking revenue increased 74.9% year-over-year, and Cloud & AI revenue grew 25.4%.
- HPE has achieved six consecutive 'beat and raise' quarters, indicating consistent operational outperformance.
- BofA adjusted its price target on Hewlett Packard Enterprise to $88 from $82, maintaining a Buy rating.
- The average analyst price target is $69.44, representing an 11.97% upside from the current price of $62.02.
Bear case
While the AI boom presents significant opportunities, HPE faces challenges related to supply chain conversion and margin pressures. The rapid growth in AI systems could lead to a focus on higher average selling prices with potentially thinner margins, impacting overall profitability. Competition in the networking and data center hardware space remains intense.
- Loop Capital adjusted its price target on Hewlett Packard Enterprise to $65 from $75, while maintaining a Buy rating.
- The P/E ratio of 28.46 is above industry averages, suggesting a potentially high valuation despite growth prospects.
- Converting the substantial backlog of AI server commitments into actual revenue depends on component availability and efficient supply chain execution.
- The lowest analyst price target for HPE is $54.00, indicating potential downside from current levels.
Fintwit's AI verdict
Hewlett Packard Enterprise has experienced significant upward momentum, fueled by its strong ties to the burgeoning AI infrastructure market and impressive quarterly results. The company's ability to secure substantial AI server commitments and raise its forward guidance paints a compelling picture for future growth.
However, investors are also considering the valuation metrics and the operational challenges of converting a large backlog into realized revenue. The market consensus reflects a generally positive outlook, but with some caution regarding the sustainability of margins in a rapidly evolving sector. The Fintwit AI model has analyzed these factors to provide its assessment.