Should You Buy DELL Right Now? A Deep Dive into Dell Technologies' AI Surge
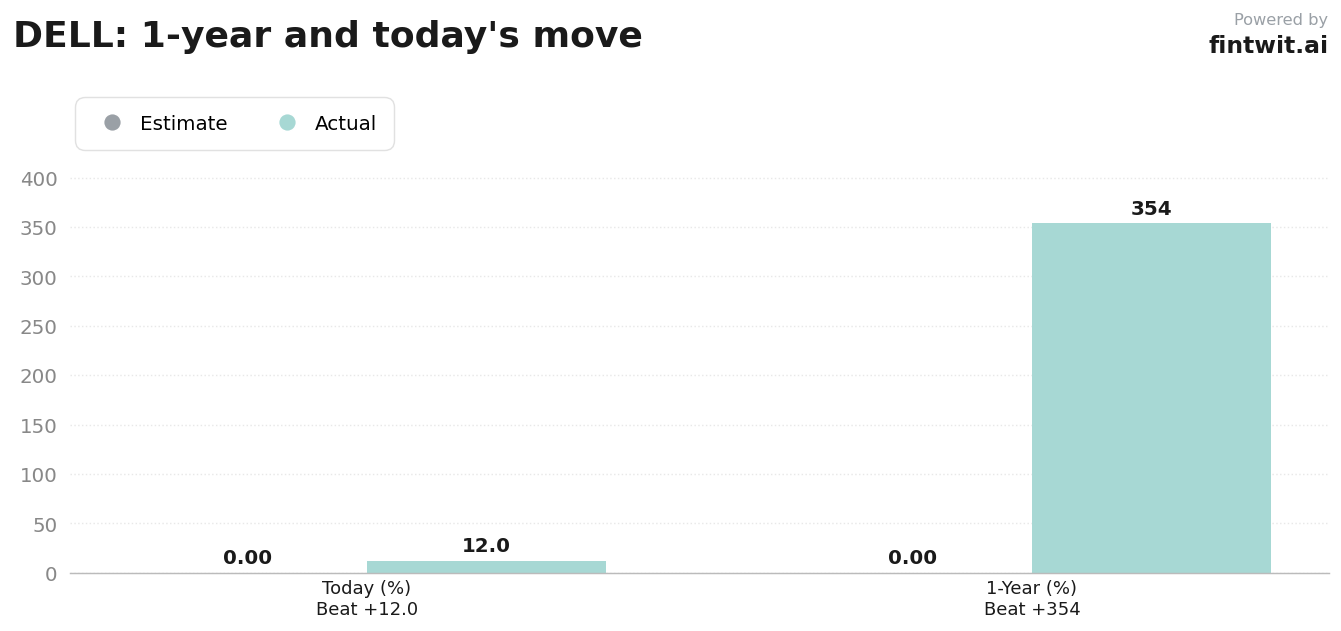
Dell Technologies (DELL) saw an 11.98% surge today, driven by strong AI server demand and analyst endorsements. We examine the bull and bear cases.
What just happened
Dell Technologies' stock experienced an 11.98% surge today, primarily driven by strong analyst confidence and the company's significant traction in AI infrastructure. CFO David Kennedy's remarks at the Goldman Sachs Communacopia + Technology Conference on September 10th were a key catalyst. Kennedy disclosed Q2 AI server bookings of $6.1 billion, matching the combined total of the prior three quarters and pushing the 12-month AI booking total to $13.2 billion.
This builds on Dell's fiscal Q2 FY2027 earnings release on September 1st, which reported record quarterly revenue of $47.0 billion, up 58% year-over-year. Adjusted EPS reached $7.04, significantly exceeding consensus estimates. The Infrastructure Solutions Group (ISG) saw an 89% growth to a record $31.8 billion, driven by AI-optimized server demand.
Dell also exited the quarter with a record $95 billion AI infrastructure backlog. The company subsequently raised its full-year fiscal 2027 revenue outlook by $25 billion to $192 billion and lifted its non-GAAP EPS guidance to $25.50.
Bull case
The bull case for Dell Technologies centers on its dominant position in the AI infrastructure market and strong financial performance. Analysts are increasingly optimistic about the company's ability to capitalize on the multi-year AI spending cycle.
- RBC Capital Markets' David Paige maintains an "Outperform" rating with a $640 target, citing Dell's strong position to benefit from the AI infrastructure spending cycle.
- Evercore ISI, also with an "Outperform" rating and a $575 target, notes that growth is increasingly driven by both enterprise and AI-related demand, not just cloud providers.
- Dell's Q2 FY2027 revenue of $47.0 billion represents a 58% year-over-year increase, significantly surpassing analyst expectations.
- Non-GAAP diluted EPS reached a record $7.04, a 203% increase, substantially exceeding projections.
- The company reported a record $95 billion AI backlog, with $60.9 billion in AI server orders booked during the quarter.
- Dell raised its full-year fiscal 2027 revenue outlook to $192 billion and non-GAAP EPS guidance to $25.50.
- CEO Michael Dell indicated a potential worsening of the structural shortage of AI-driven computing capacity in 2027, suggesting long-term demand.
Bear case
Despite significant momentum, the bear case for Dell Technologies highlights valuation concerns and potential operational headwinds. These factors could temper future growth or impact profitability.
- Public.com maintains a "Hold" rating, reflecting caution on valuation given Dell's P/E ratio of 33.00.
- Potential risks include rising memory costs, which could compress gross margins.
- Sustained supply constraints, while indicating demand, could also limit Dell's ability to fully capitalize on its backlog if not managed effectively.
- The current rally may have already priced in much of the anticipated AI growth, leaving less upside.
- Conversion of the substantial $95 billion AI backlog into shipments needs to be validated to ensure it represents actual demand rather than just increasing the backlog.
Fintwit's AI verdict
Fintwit's AI has analyzed the latest data and market sentiment surrounding Dell Technologies. The model has processed the company's recent earnings, analyst revisions, and its strategic positioning within the AI hardware sector.
Considering the substantial AI server bookings, the record backlog, and the upward revisions to full-year guidance, the AI has formulated a definitive stance on Dell's investment potential. The verdict reflects a comprehensive evaluation of both the opportunities and the risks identified in the current market environment.