Should You Buy DY Right Now? Analyzing Dycom Industries After the Q2 Sell-Off
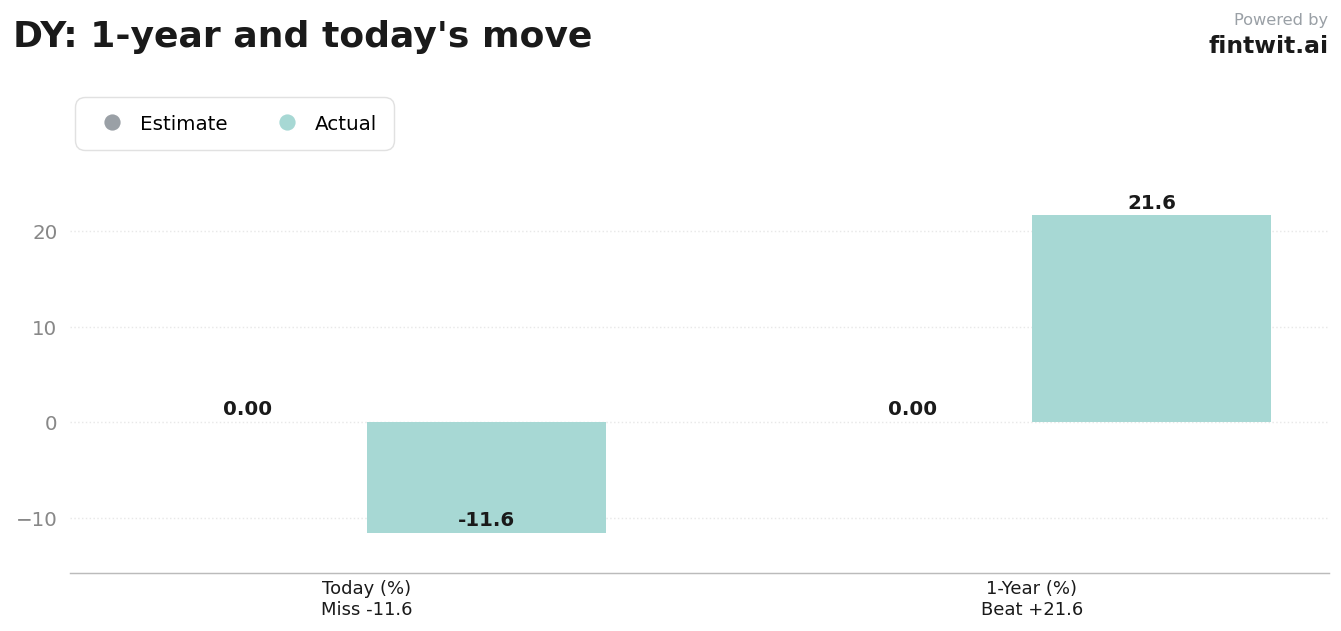
Dycom Industries shares fell 11.62% after Q2 earnings. We analyze the backlog, margin headwinds, and the bull vs. bear case for the engineering firm.
What just happened
The market reacted sharply to the fiscal Q2 2027 earnings release, which highlighted a divergence between record operational scale and short-term margin efficiency. While Dycom achieved record revenue, the decision to push $150 million of wireless program revenue into fiscal 2028 created a temporary growth gap that investors punished.
The stock is currently trading below both its 50-day and 200-day moving averages, signaling a shift in technical momentum. This retreat follows a period of strong performance where the stock had gained 21.63% over the trailing 12-month period.
Bull case
- Dycom maintains a record backlog of $12.24 billion, providing significant revenue visibility for future quarters.
- Contract revenues grew 45.6% year-over-year in Q2 FY27, demonstrating strong demand for digital infrastructure.
- Wells Fargo analyst Eric Luebchow maintained an Overweight rating and raised his price target to $650.00, citing long-term growth potential.
- B. Riley Securities analyst Liam Burke maintained a Buy rating and increased his target to $625.00.
- The company authorized a new $150 million share repurchase program that remains active through February 2028.
Bear case
- Communications segment margins declined by 134 basis points, raising concerns about cost management in a high-inflation environment.
- Passage Research maintains a Sell rating with a $290.00 price target, arguing the stock is overvalued at 14.1x EV/EBITDA.
- The company's Q3 guidance midpoint failed to meet the consensus expectations of some institutional analysts.
- The deferral of $150 million in wireless revenue suggests potential project execution delays or client-side budget shifts.
- The stock currently trades at a P/E ratio of 36.38, which some investors view as a premium valuation given the recent margin volatility.
Fintwit's AI verdict
The algorithmic assessment of Dycom Industries balances the massive $12.24 billion backlog against the immediate margin headwinds reported in the latest quarter. While the technical setup shows a clear breakdown in momentum, the fundamental demand for fiber and data center infrastructure remains a primary driver for the firm's long-term outlook.
Investors are currently weighing whether the 11.62% correction provides an entry point or if the valuation multiple requires further compression. The following verdict reflects a synthesis of current analyst sentiment and the company's capital allocation strategy.